Dog Food Sales Have Stalled Except in the Refrigerated Aisle, and Freshpet’s Investors Disagree on How Long That Lasts

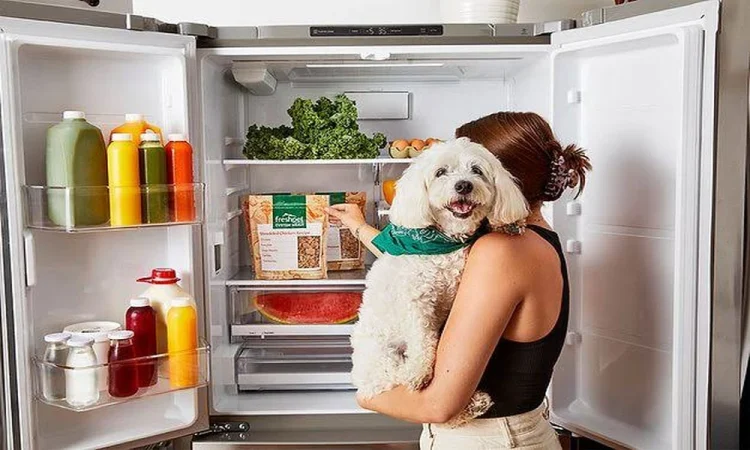
General Mills sold $2.6 billion of pet food in its 2026 fiscal year, and organic sales in that business fell 3%. Freshpet, a company less than half that size, grew second-quarter net sales 15.5%.
The two results came from the same U.S. dog food market. NielsenIQ data reported late last year showed total dog food sales down 0.2% over 12 months. Kibble sales slipped 0.5%, and canned and other wet food fell 3.2%. Refrigerated and frozen dog food, the small segment Freshpet dominates, rose 13.4%, an increase of about $208 million in sales.
Nearly all of the category’s growth sits in a single, refrigerated aisle. That split has shaped how food companies spend money, and it has divided the institutional investors who own Freshpet’s stock.
Where the Growth Comes From
Packaged Facts expects fresh, frozen and refrigerated pet food, roughly a 7% slice of U.S. dog and cat food sales in 2025, to expand 15% to 20% a year. Its forecast for pet food overall is 3.7% annual growth through 2029. The firm also calculated that “frozen/refrigerated pet foods are growing fast enough to bring up overall dog food growth by over one percentage point.”
The demand reflects a change in how owners think about pets, which the industry calls humanization. Dogs are treated as household members, and their food is judged by standards owners use for their own meals. Fresh food, cooked and refrigerated rather than extruded into shelf-stable kibble, is the most direct product response to that change.
Freshpet has captured most of the benefit. NielsenIQ omnichannel figures cited by the company put its share of U.S. dog food and treats at 4.3%, with dollar sales rising faster than those of any other dog food brand. Second-quarter net sales reached $305.6 million. Volume rose 15.7%, and price and mix subtracted 0.2%, meaning the gain came from selling more food rather than raising prices.
Chief Executive Billy Cyr summarized the quarter in the company’s earnings release: “we grew significantly faster than the category, improved margins, and produced strong cash flow.”
Freshpet’s full-year 2025 net sales rose 13% to $1.10 billion, with volume up 12% and price and mix adding 1%. Adjusted EBITDA climbed to $195.7 million from $161.8 million. Cyr described that year as “delivering growth well in excess of the dog food category, surpassing $1 billion in net sales for the first time.”
General Mills’ North America Pet segment posted fiscal fourth-quarter net sales of $702.4 million, up 4%, with cat food growing at a double-digit rate and dog food at a low-single-digit rate. Organic net sales for the quarter fell 3%, and all-channel retail sales declined 1%, which the company attributed mainly to retailer inventory changes. Segment operating profit for the full fiscal year was roughly flat at about $499 million. Cat food, rather than dog food, supplied most of the growth inside one of the country’s largest pet portfolios.
A Concentrated Customer Base
Freshpet’s growth rests heavily on a minority of households. Ultra- and super-heavy buyers, grouped by the company as MVPs, generated 71% of sales and spent about $515 each on average, five times the typical household. Their ranks grew 11% in a year.
Broader reach is growing more slowly. Total household penetration rose 5%, and the average buying household spent about $117, up 7%. Chief Operating Officer Nicki Baty, who becomes Freshpet’s president on Oct. 20, has described the company’s goal as moving from a trial-driven model toward a more durable consumer franchise, which in practice means converting occasional buyers into the kind of households that already generate most of the revenue.
Committed buyers are less likely to trade down in a weak economy. A business that depends on them, however, has fewer new customers to replace any who leave.
The Price Problem
Cost is the most common reason owners stay with kibble. A 2025 survey of 1,200 pet owners in six countries, conducted by Yummypets and PETS International, found that 64% of U.S. respondents named price as the key barrier to adding alternative foods to their pets’ diets.
Freshpet’s management has acknowledged the pressure. Cyr said on the second-quarter call that higher gas prices and weaker consumer sentiment had made shoppers less willing to trade up in pet food and other categories. Chief Financial Officer John O’Connor framed the forecast around those conditions. “To achieve the low end of our sales guidance, we assume the macro environment stays the same as it is today,” he said. The low end of the range assumes little to no sequential growth in sales or household penetration.
U.S. Bureau of Economic Analysis data show that pet spending growth slowed during the 2001 and 2008 recessions but did not turn negative, and pet spending more than doubled between 2010 and 2023. That record covers the pet category broadly. No comparable data exist for refrigerated dog food through a full recession, because the segment was a fraction of its current size in 2008.
How the Incumbents Are Responding
General Mills has pursued the fresh segment from outside it. The company acquired Whitebridge Pet Brands for $1.45 billion in December 2024, which lifted reported pet sales, and introduced a refrigerated Blue Buffalo line, Love Made Fresh, across the country in October 2025. Retail sales of the line rose roughly 80% in the company’s fiscal fourth quarter and 30% in the quarter after.
“We remain bullish on the long-term opportunity for Blue Buffalo in the fresh feeding segment,” General Mills Chief Operating Officer Dana McNabb said in July.
The scale gap remains wide. Love Made Fresh held about 6,000 refrigerated displays in September 2026, while Freshpet operated 39,938 coolers in 30,721 stores at midyear. Fresh food must be kept cold from factory to shelf, so a new entrant has to fund refrigerated plants, refrigerated freight and in-store equipment before it sells much product. General Mills found that its retail representatives needed to visit stores more often to keep its displays stocked, an operational cost that does not apply to dry food.
Logistics expenses at Freshpet rose to 6.9% of net sales in the second quarter from 5.7% a year earlier, pushed up by fuel prices and limited trucking capacity. Capital spending is running at about $150 million a year.
The Financial Case Management Is Making
Freshpet has held prices roughly flat while widening margins. Adjusted gross margin rose to 48.6% in the second quarter from 46.9%, and adjusted EBITDA increased to $52.2 million from $44.4 million. The company generated $27.4 million of free cash flow in the first half of 2026, after posting its first positive full-year free cash flow, $12.4 million, in 2025.
Guidance has moved up twice this year. Freshpet began 2026 forecasting net sales growth of 7% to 10%, raised that to 8% to 11%, and after the second quarter lifted it again to 10% to 12%. Adjusted EBITDA guidance now stands at $210 million to $220 million. For 2027, the company targets adjusted gross margin of at least 49% and an adjusted EBITDA margin of 20% to 22%.
O’Connor tied the upper end of the 2026 range to marketing results. “To meet or exceed the high end of our guidance, we would need to see greater impact from our advertising,” he said. Freshpet cut media spending to 13.4% of net sales in the quarter from 15%.
Investors Moving in Different Directions
Second-quarter 13F filings show institutions both adding and trimming. One tracker counted 84 funds increasing Freshpet positions and 99 reducing them.
The largest holders mostly added at the margin. BlackRock, with about 5.9 million shares, increased its stake slightly. Capital World Investors, Vanguard and State Street also added. Wellington Management increased its holding 11.8% to about 2.8 million shares, AllianceBernstein added 21.2%, and Dimensional Fund Advisors raised its position 55.9%.
Wasatch Advisors, which held more than 8% of the company as recently as April, cut its stake 31.9% to about 2.8 million shares. Among hedge funds, Marshall Wace raised its position 68.8% to about 1.4 million shares, Balyasny Asset Management held a similar amount, and Citadel Advisors held close to 900,000 shares after a small reduction.
Armistice Capital, a New York hedge fund best known for healthcare investments, sat on the buying side, raising its Freshpet holding 15% to about 1.3 million shares. StockZoa valued the June 30 position near $75 million, ahead of the fund’s reported Amazon stake. The fund also holds shares of Central Garden & Pet, a pet supplies and lawn-and-garden company, giving it a second piece of pet-category exposure.
The Next Test
Freshpet has told investors that third-quarter reported growth will be reduced by just over 2 percentage points, the result of comparisons against a large warehouse club expansion and a shift in July Fourth ordering in 2025. Household penetration growth may stay subdued while inflation weighs on spending, the company said.
The broader question for holders on both sides of those 13F filings is whether a $56 billion U.S. pet food industry with flat dog food sales keeps shifting dollars toward the refrigerated aisle when budgets tighten. Freshpet’s second quarter showed volume growth near 16% at steady prices. Its third-quarter report will show whether that pace holds against tougher comparisons and a weaker consumer.